Financial Planning for Women: How to Prepare for Career Breaks, Retirement and Promote Financial Security
Helen Thomas explores the different financial realities facing women and the practical steps women can take to build financial security.
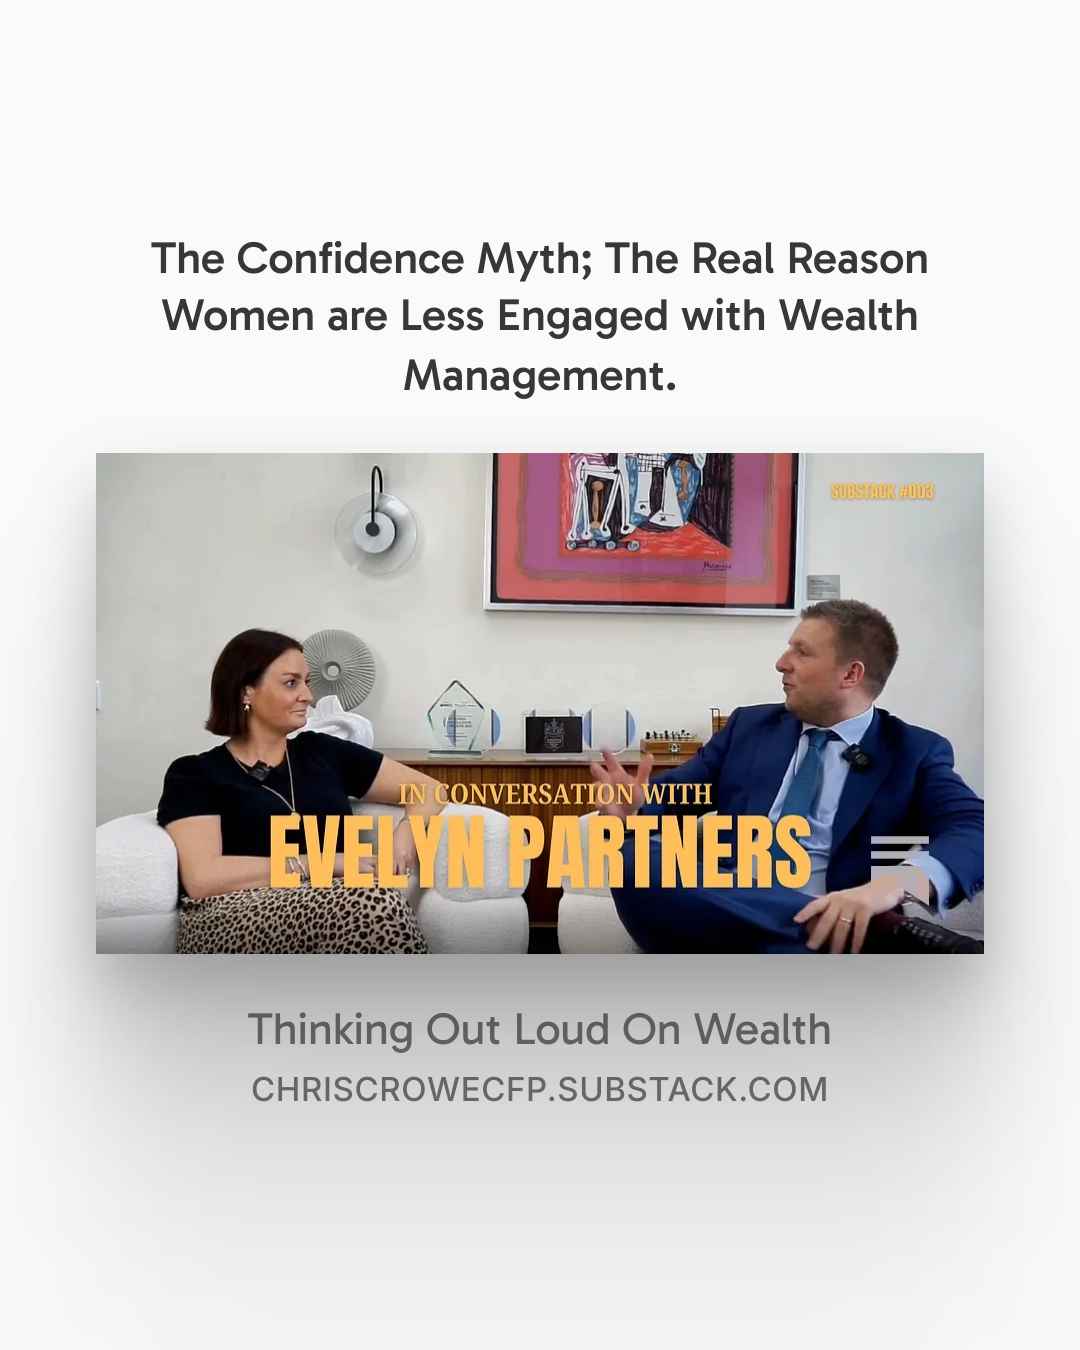
For years, the industry has been aware of a lack of engagement amongst women when it comes to financial planning and an assertion that it was due to a lack of confidence. But a report published by Compassion in Financial Services Hub has made short shrift of this. Instead, the report points to the realities of women's lives, including the weight of the mental load, as barriers to engagement. It also spoke to an industry that persists in modelling financial plans that adhere to the linear careers of men and failing to factor career-breaks or part-time working that are more common amongst women.
As a woman working in financial services, ensuring women have access to the quality financial advice they deserve is something I feel very passionate about. It’s one of the reasons why I was so pleased to co-host an event with Evelyn Partners earlier this year, Her Wealth, Her Terms, where we explored some of the issues facing women when it comes to financial planning.
Our director Chris Crowe sat down with Harriette Collings, Director of Business Development at Evelyn Partners - the firm being one of the founding members of Compassion in Financial Services Hub - where they went into more detail about some of the issues raised by the report - find the conversation here.
My own conversations spurred me to think about the practical things women can be doing to take charge of their financial futures.
In this article, I will;
- Explore universal good financial practices
- Identify the different financial realities facing women
- Examine how career breaks can be factored into a financial plan
- Explore how retirement planning is different for women
- The value of seeking professional help
Know your financial picture
The first step toward achieving any financial goal is to understand your current financial situation. That means creating a clear picture of what you already have: your accounts, your debts, and, if you're in a relationship, what's shared and vitally, what isn't.
Watch: How Women Can Build Wealth Despite the Pay Gap
In this video, I share five practical strategies women can use to close the wealth gap: from paying yourself first and maximising employer contributions, to building assets in your own name and making financial planning a joint decision. I also cover how to plan career breaks without losing ground, including how to build flexibility into your plan during your highest-earning years.
Get your documents in order.
Know what bank accounts you hold, where they are, and what interest (if any) they're paying. Understand your credit card limits and make a habit of paying them off in full each month. If you're in a relationship, get clear on what's held jointly, who pays for what, and when. And, if you're an expat, keep a running record of savings, investments and pensions in each country you've worked in — the policy number, the provider, and whether you have online access. It sounds basic, but it's the single most common gap we see, and it's also the fastest thing to fix.
Know what’s coming in and what’s going out.
Today, there are many banking apps that will help you do this automatically. But broadly speaking, you need to know all your obligations – credit cards, mortgages, bills, everything; then this needs to be balanced against income. We call this cash flow modelling and it’s one of the first things a professional financial adviser will do with you. Once you know your numbers, you should be better able to identify any surplus. A common issue we see is that a surplus, if left unidentified, is spent without realising.
The power of consistent saving
Saving and Investing.
Once you’ve identified your surplus, you can seek to put this money to better use via savings and investments. There are myriads of savings and investment options available. What works best for you will depend on your circumstances and financial goals. It’s another reason to speak to a professional as they can help source opportunities that best fit your needs.
The amount matters less than the habit.
Choose a figure that is manageable and realistic rather than something aggressive you'll cancel after a couple of months. The benefit of investing consistently and early means there’s more time for compounding to do the heavy lifting. Compounding is the interest earned on interest; put simply, a relatively small amount invested early enough can outperform a much larger amount invested later. Our explainer on the power of compounding goes into this in more detail.
Make saving and investing proportional.
It sounds obvious but the amount you are saving and investing should rise as your income does. This means ensuring that lifestyle expenses are kept in check. Enjoying a higher income is fine; just remember that looking wealthy and being wealthy are not the same thing.
Optimise tax-advantaged and employer-funded schemes.
It can be worth talking to your employer before your next pay rise or bonus and asking whether they can direct some or all of the additional amount into your EPF or company pension scheme rather than paying it out as salary. This comes with its own tax-advantages and can help build your long-term retirement savings with meaningful financial benefits.
Women Face different financial realities
Beyond building the universal good financial habits, it’s important to note there are different financial challenges women are more likely to face, principally; longer life expectancies and career breaks. The combination of both may then result in a continued reliance on the financial pots built by a spouse. As such, women need to be aware of pension and estate rules that don't always treat a surviving spouse the same way they treat the original member. These differing realities need to be recognised and planned for as a part of any comprehensive financial plan.
Factoring career breaks
Women are still more likely than men to take career breaks, largely due to caregiving responsibilities, and the way the labour market treats those breaks compounds over a career. Research published in Labour Economics found that employers rank candidates with employment gaps less favourably overall, with training-related breaks penalised least and caregiving-related gaps penalised more. Because women are both more likely to take a caregiving break and more likely to take a longer one, that penalty doesn't stay a one-off; it can feed into a gender pay gap over the course of a career, with real financial implications.
Closing the gap: what can women do?
Plan ahead of a maternity leave
Before going on maternity leave, check what your employer offers. You can also speak to a recruiter to ask what the standard is for your industry to check whether what you’re being offered is on par. Additionally, find out what your partner’s parental benefits package looks like. Being armed with this information will help you and your partner make more informed decisions and have more productive conversations with your employers.
Plan for longer career breaks
There's no universal figure for how much a multi-year career break may cost; it depends on current spending, expected retirement spending during the break, and its length. This said, there are some standard principles that apply when developing a financial plan to factor these longer breaks. Firstly, start with your basic costs (rent or mortgage share, household bills) for the expected duration, add anything specific to the break itself (childcare-related costs, for example), and offset that against any income that might still be coming in, such as employer or state parental pay or caregiver allowances, as well as wider income streams. Again, this information can help you stay on track with your long-term goals.
Plan for an unplanned break
Life isn’t always smooth sailing; it’s why it’s always worth having an emergency fund in place. I’ve worked with a client who was able to take unpaid leave to care for her mother, without financial strain, purely because she had built an emergency fund covering more than six months of expenses. That fund meant she could be present for her mother without the added weight of worrying about her finances.
Treat financial planning as a joint responsibility
Career breaks can mean that you’re relying on a partner’s income to support you. In my experience, this can see some women stepping back and letting their partner take the lead on finances, which then risks women being sidelined. It’s a phenomenon Harriette comments on;
"One partner naturally takes the lead on financial matters 'for now'. The challenge is that temporary arrangements can become permanent... The risk is that the imbalance often remains invisible until a major life event occurs. Illness, divorce or bereavement."
So even during a career break, it's always important to keep a handle on the finances and remain involved in financial decisions. Bearing this in mind, it's worth holding investments in both partners' names, jointly or separately, so that both partners have financial independence and access to funds, particularly in an emergency.
Women need to factor in a longer retirement
Women have differing considerations when it comes to retirement planning as they tend to live around longer, earn less over a lifetime, and due to their older age, spend more of their later years in poorer health. All these factors then affect how much a long-term retirement plan needs to cover and for how long. Potential long-term care needs should also be factored into any retirement savings strategy.
So, what can women do in preparation?
Understand your pensions
If you’re an expat, you are more likely to have pensions spread across multiple jurisdictions, not only does that create complications in itself – but every pension also works differently. Whether EPF or a UK workplace pension, each has its own rules on investment choice, access age, and what happens to it on death. If you've worked across several countries, as most expats have, it's worth mapping each one individually. You can learn more about pension planning as an expat here.
Understand your partner’s pension
In some cases, UK SIPPs being one example, a surviving spouse can receive 100% of what the deceased was drawing. In others, particularly UK "final salary" schemes, the widow's pension is typically reduced to around 50–60% of the original income, which can materially change the financial situation and long-term financial security of a surviving spouse's standard of living. This is a critical point for expat spouses who haven't been able to build a pension of their own.
Ensure beneficiaries are named
The provider needs to know who to pay if something happens to you, the same also applies to your partner. It’s worth noting that EPF specifically does not allow foreign nationals to nominate a beneficiary. Second, keep your will current and review it regularly; however clear your intentions are, they only count if they're written down. Our Beneficiary Trust guide and estate planning checklist both cover this in more depth, and if you're part of a mixed-nationality couple, our guide is a useful companion read.
Building a retirement pot while you’re not working.
If you are away from the workforce or if you’re an expat spouse who, for visa reasons, is unable to work, a pension is unlikely to be the right vehicle for you to build a retirement pot. As such, it’s worth considering investment accounts as most have no minimum investment amount and no minimum access age, making them a practical way to start saving for retirement and building long-term financial security during a transition period.
Seek professional guidance from a regulated financial adviser
Given these complexities and many more besides, I always recommend seeking independent financial advice. When looking for an adviser, a good rule of thumb is to find a financial adviser who begins the planning conversation with you, not with products. The first conversation should focus on your current financial situation and your short-term and long-term objectives. Products aren't irrelevant; they're part of the eventual solution, but a plan ought to be built around you.
What should women do next?
Taking charge of your financial future does not require having every answer today; it begins with understanding where you stand and taking one practical step at a time. Building consistent saving habits, careful planning for career breaks and remaining involved in household financial decisions can all help strengthen your long-term financial security. Because women’s lives and careers do not always follow a linear path, financial plans need to be flexible enough to reflect those realities. With the right financial knowledge, regular reviews and professional guidance where needed, you can build a comprehensive financial plan that supports both the life you have now and the financial future you want.
Whether you're building your financial cushion, planning a career break, or untangling pensions across three countries, I'm happy to start any conversation. Connect with me on Linkedin or email me at helenthomas@melbournecapitalgroup.com
This article is for general information only and does not constitute financial advice and should not be construed as such. Outcomes depend on individual circumstances, and independent, professional advice should be sought before making any financial decision.

Explore our Insights
Our team of global experts share their perspective on markets and news from the company.