What Financial Preparedness Really Means for Women
I've sat in a lot of rooms where people talk about money in theory, but never in practice. Savings? Investments? For women, it can mean knowing what you own, having access to money, being involved in financial decisions and understanding how life changes can affect your future.
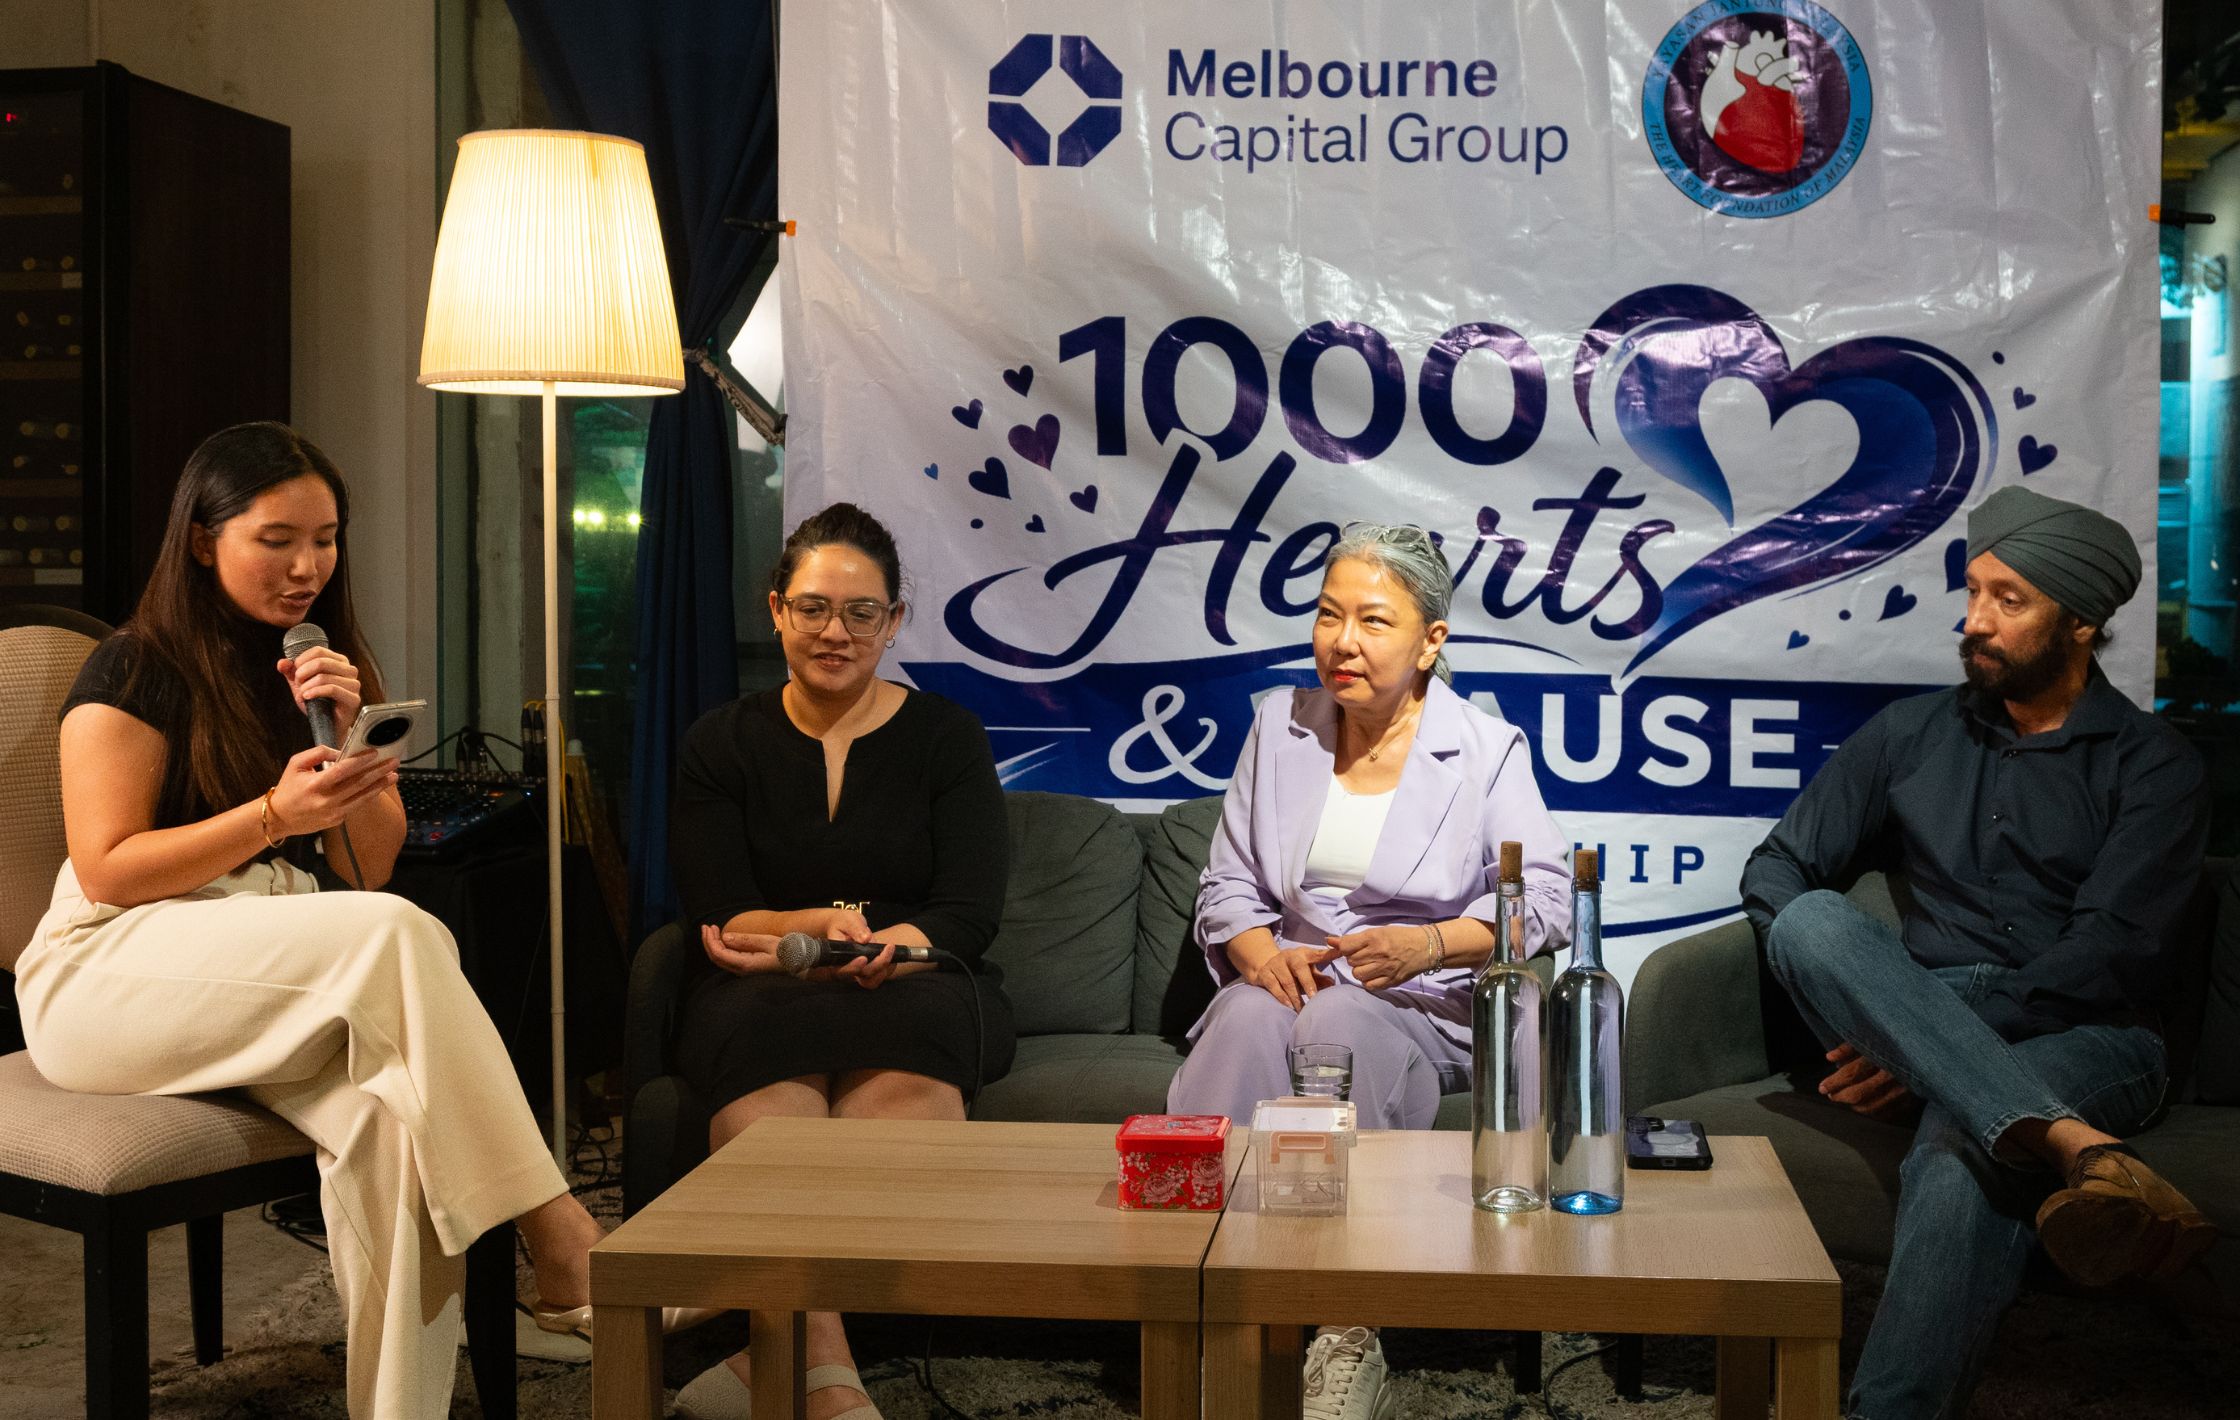
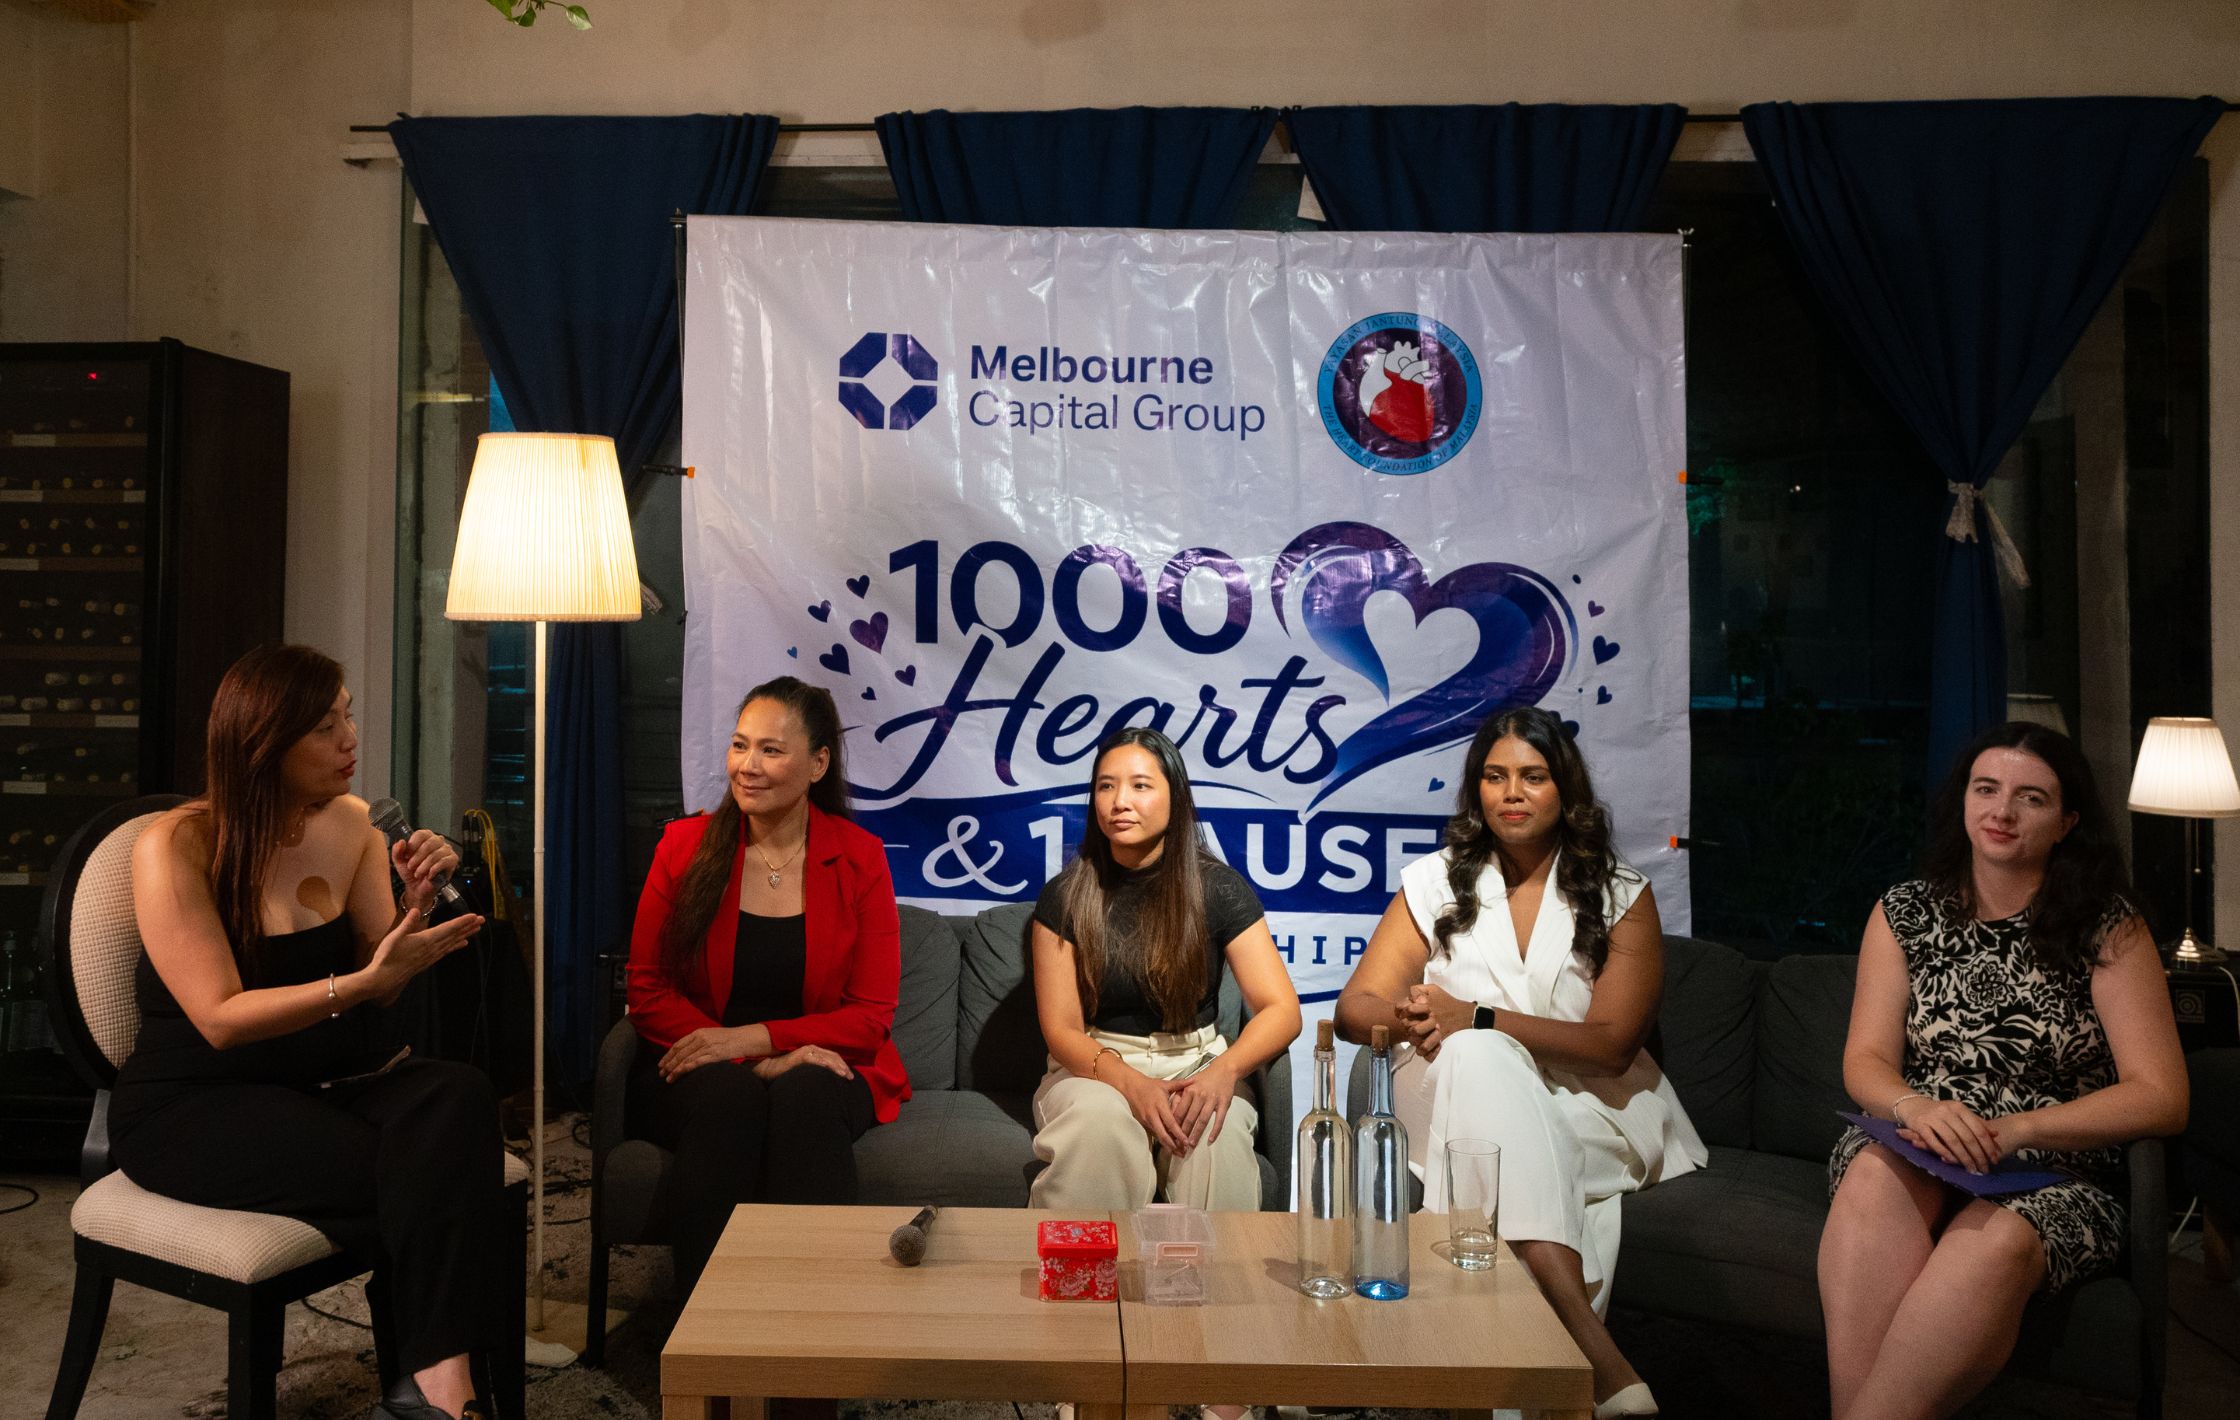
That was the central message of the wealth panel at Health.Wealth.Her. held on the 12th of August, in support of Yayasan Jantung Malaysia, and it’s stayed with me since: the more informed and involved you are, the more options you have.
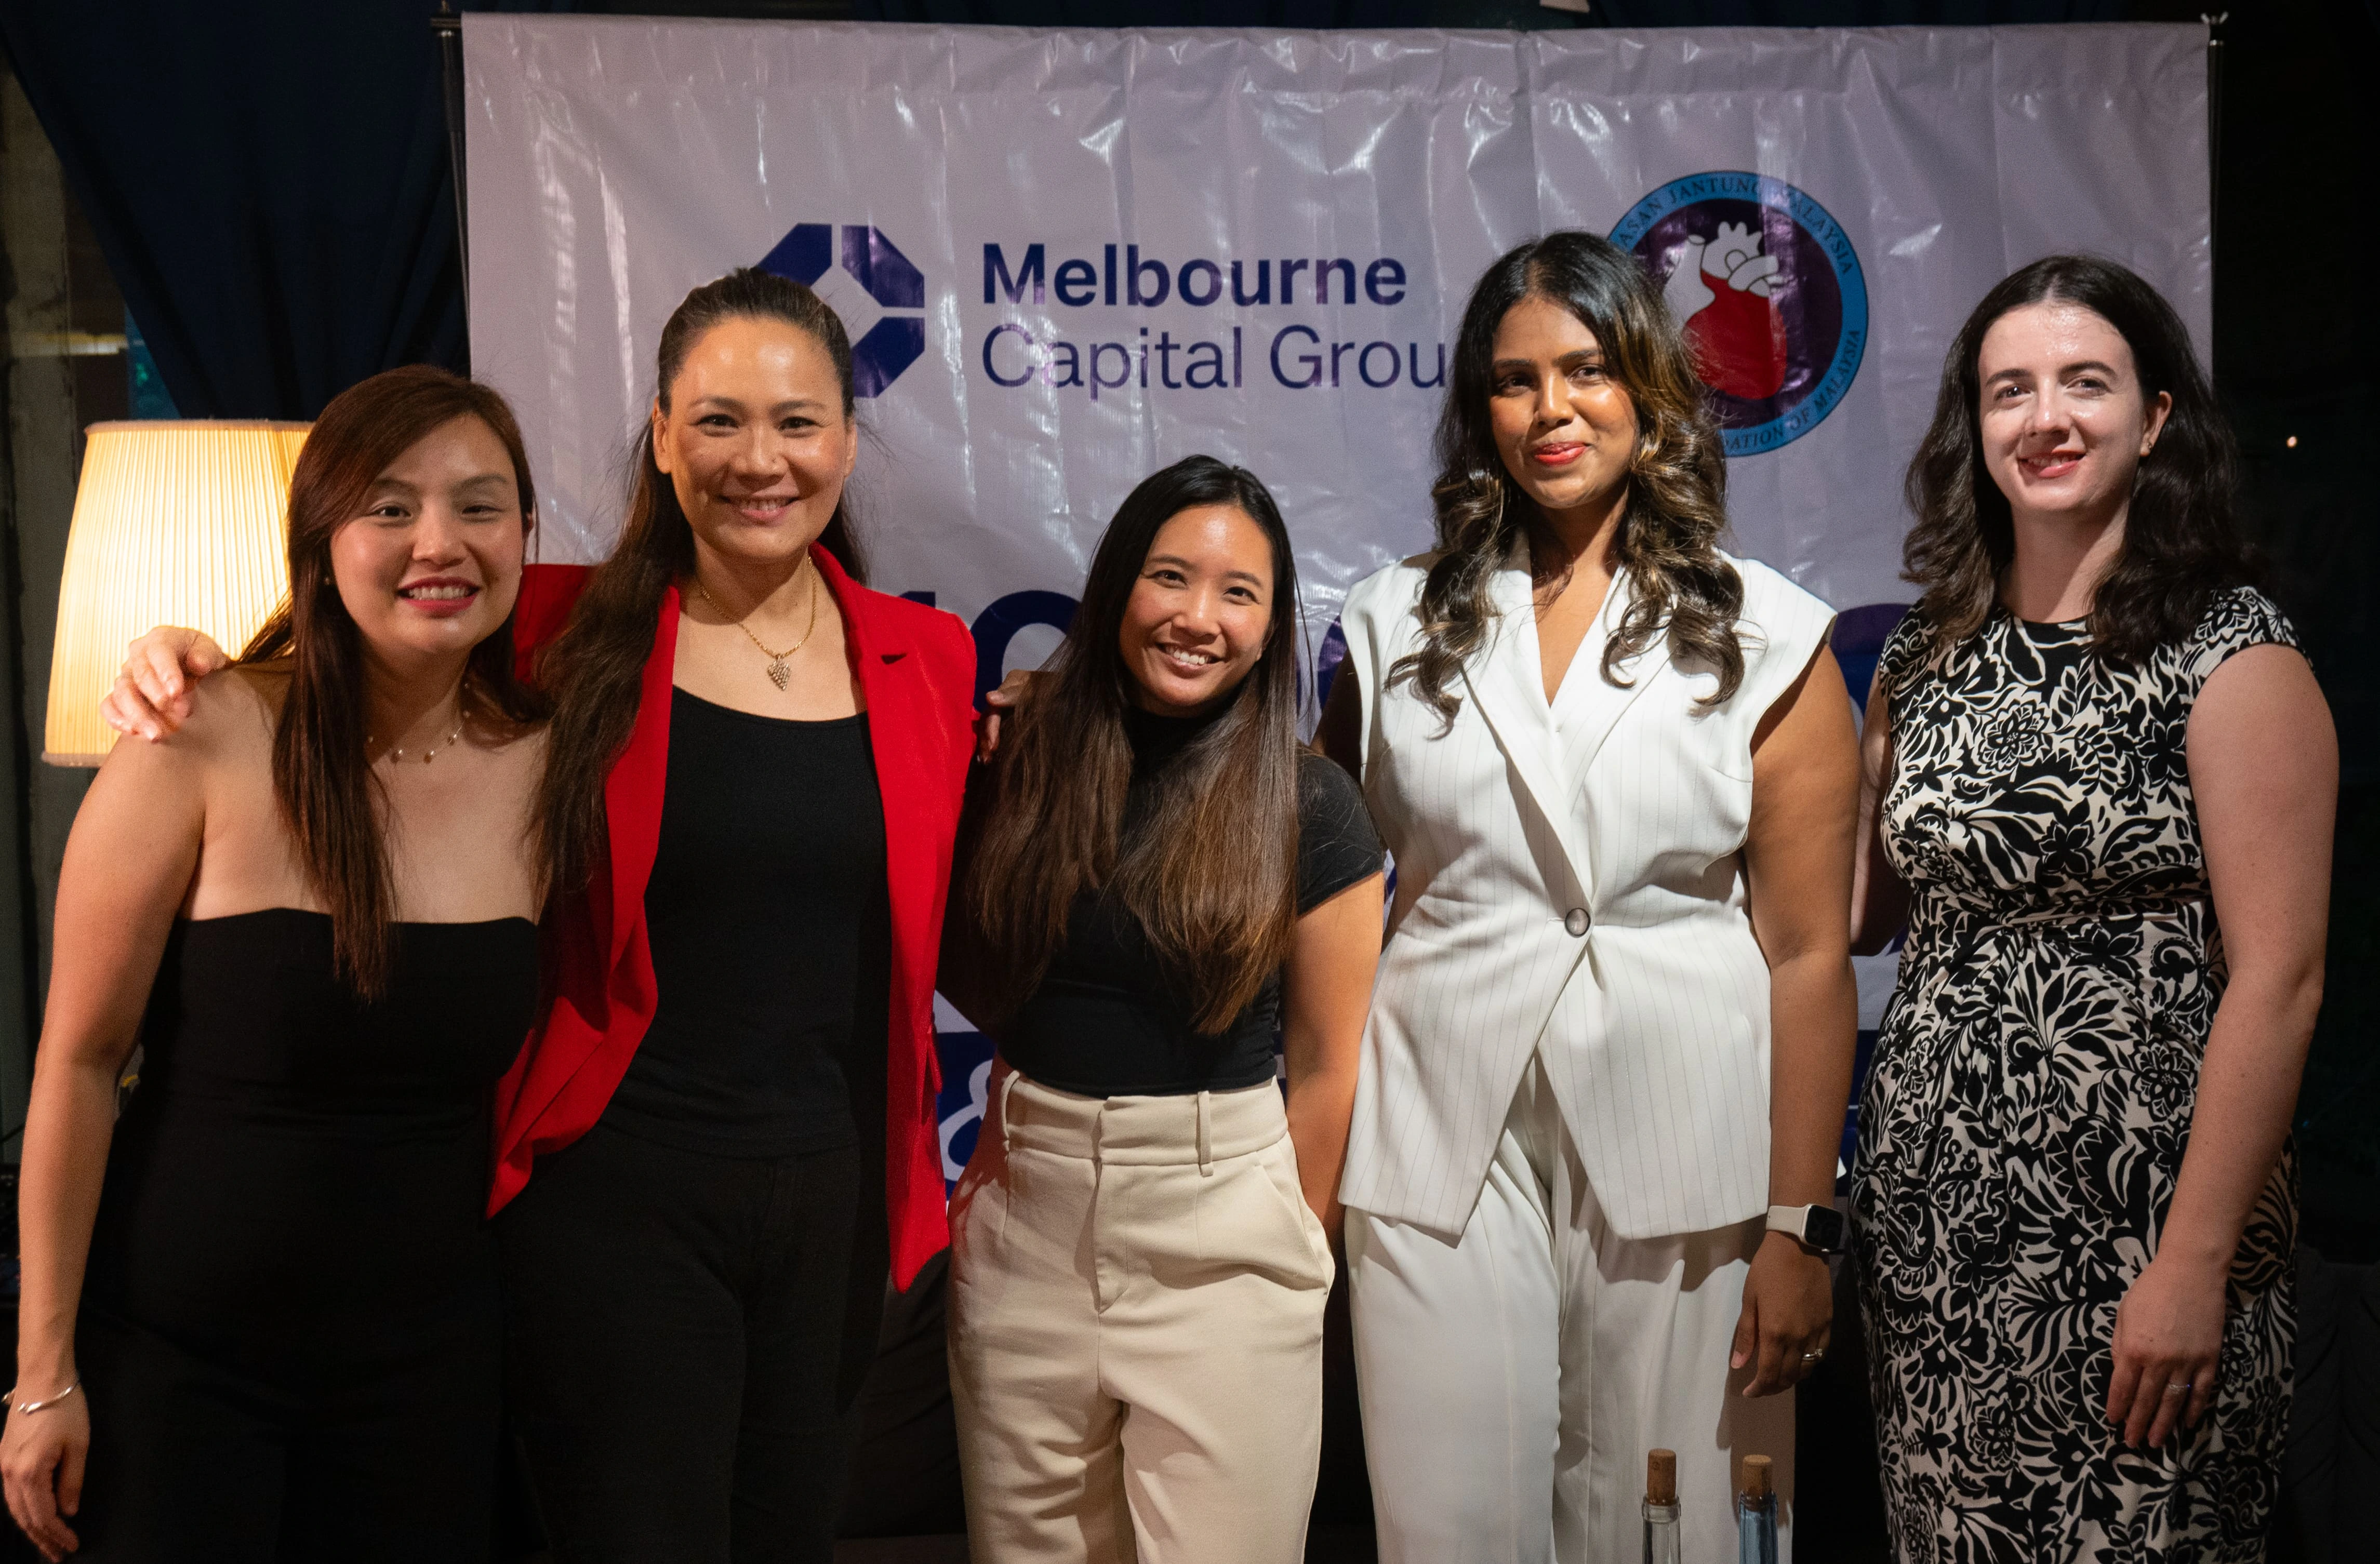
The wealth panel was moderated by Nicole Sue (Business Manager, Melbourne Capital Group) and brought together Rina Ho (CEO and Founder, Pistil), Rozana Halpin (Executive and Leadership Coach, KCom Academy), Piya Balakrishnan (Family and Divorce Lawyer, Piya Law Chambers), and myself, Helen Thomas (Private Wealth Manager, Melbourne Capital Group).
Listen To the Panel Discussion Here
Protection Is Not a Feeling. It Is a File.
There is a moment in Strangers: A Memoir of Marriage that captures an idea family and divorce lawyer Piya Balakrishnan put simply:
“Protection is not a feeling; it is a file.”
Decades into her marriage, a wife discovers that she has no real claim to anything within it. Not because her husband was cruel, but because she had never asked the questions that mattered.
Piya distilled those questions into three practical starting points, and I’d encourage any woman to sit with them:
Do you know what you own? Do you have access to something that is solely yours? And is a copy of your key documents kept somewhere your partner cannot reach?
The numbers back up why those questions matter.
UK research by Legal & General found that women’s household income fell by a third in the year following a divorce, almost twice the drop seen by men (18%). I haven’t seen an equivalent study closer to home in Malaysia, but it matches what I see in my own practice: the financial fallout of a separation is rarely split evenly, and preparedness is what narrows that gap before it opens.
That idea became a thread running through the wider conversation. Preparedness is not a single document, decision or bank account. In my experience, it rests on four things: knowledge, confidence, capability and a strong support system. None of them can be completely handed over to someone else, no matter how much you trust them.
It means knowing where you stand before you are forced to find out. Staying informed. Protecting your health. Building a financial buffer before you need one.
Nicole Sue compared it to the familiar instruction on an aeroplane safety card: put your own oxygen mask on first. Not out of self-interest, but because you are in a far better position to care for others when your own foundations are secure. I think about that analogy often with clients.
The Conversations Women Are Having Alone, and Shouldn’t Be
The hardest financial conversation many women have is not with a bank. It is with the person they share their life with. In my work, I’ve found the difficulty is rarely a lack of awareness that money needs discussing. It’s not knowing how to begin.
Sometimes the best starting point is deliberately practical: bring both partners into financial planning meetings, make sure each person is part of the conversation, and ask simple questions such as, “Where can we access money quickly if something goes wrong?” before circumstances make the answer urgent.
Removing some of the emotion can help. Piya suggests treating financial preparedness much like renewing an insurance policy: routine, administrative and simply part of keeping life in order.
Yet the willingness to have those conversations can reveal something deeper. As Nicole observed, a partner who is comfortable engaging in them is telling you something. So is one who repeatedly avoids them.
Part of the difficulty begins long before a relationship does. Women are often conditioned to accommodate others, keep the peace and avoid creating tension. Over time, that can make conversations about money, ownership and protection feel more confrontational than they need to be.
There are signs, however, that those expectations are changing. Leadership coach Rozana Halpin pointed to her own daughter, who sees a prenuptial agreement and a clearly divided household budget as natural conversations to have before marriage. Not because she expects the relationship to fail, but because clarity is part of entering it well prepared.
That openness has to work both ways. If one partner continually avoids the subject while the other is left to keep raising it, eventually the conversation may disappear altogether.
Financial preparedness therefore requires more than having the right documents in place. It also means creating the kind of relationship in which money can be discussed openly and calmly before a crisis makes the conversation unavoidable.
What Financial Independence Actually Looks Like in Practice
One of the questions raised was both simple and difficult:
“If I’m not financially independent right now, and things become unsafe, what options do I actually have?”
I was asked that question directly, and my answer was unequivocal: You always have options, even if they start small.
Those options may begin small. A conversation with a financial planner. Speaking to a divorce lawyer. Understanding what resources are available. Or simply recognising that stepping away from a career to support someone else’s does not mean surrendering your own financial future.
Rina Ho, CEO of Pistil, reflected on her own career as another version of that same principle, without the crisis attached.
Before she had a product, she attended industry events to test the idea. Before she had funding, she spoke to prospective customers. Rather than leaving her job immediately, she saved aggressively and joined an accelerator, building towards the transition gradually instead of making the leap all at once.
She was candid, too, about the barriers women still face raising capital. As she shared with the room, women-led companies may outperform, yet they still receive only around 15 per cent of available funding. Her response is practical rather than symbolic: make use of the routes that already exist.
Free Women in Tech programmes run by companies including Microsoft, Google and AWS can offer skills, networks and a route into the industry without waiting for the industry itself to open the door.
The Years Out of the Workforce Aren’t Lost. Here’s What the Law Says
One of the most important points of the evening was also one of the quietest, and it is the one I want more women to hear.
Piya explained that under Malaysia’s Law Reform (Marriage and Divorce) Act 1976, contribution to a marriage is not viewed purely in financial terms. Caregiving, running a household and supporting a family can all carry weight when matrimonial assets are divided.
In other words, years spent outside the workforce are not simply an absence from a woman’s financial story. They are part of it.
Piya returned to this point because, in her experience, many women only discover it when they are already facing separation. By then, some have spent years believing that time away from paid employment meant they contributed less and are therefore entitled to less.
Sometimes one conversation with the right professional can change that understanding completely.
The first step towards a fairer outcome may simply be realising that the contribution you made was never invisible in the first place.
Why Confidence, Not Information, Is the Real Barrier
This is the point I feel most strongly about, because I see it in my own practice more than any other. For many women, the biggest barrier to financial independence is not a lack of financial information. It is a lack of confidence in using it.
The financial industry has not always helped. Too often, its language makes money feel more complicated, technical and intimidating than it needs to be.
I shared the story of a client who had built a successful marketing career at L’Oréal before stepping away from it to follow her husband abroad. Twenty-five years later, after a divorce, she came to me having lost so much confidence in her own judgement that the first task was not to build a financial plan. It was to help her recognise what was already there: the knowledge she had accumulated, the decisions she was capable of making and the professional confidence she had once carried easily.
Sometimes financial independence does not begin with learning something new. It begins with remembering what you already know.
The Bottom Line: Preparedness Creates Options
Financial independence does not mean doing everything alone. It means having the knowledge, confidence and, knowing where to start and having access to make informed decisions about your own future. Women’s financial preparedness is not about expecting the worst. It is about making sure you still have options if life changes.
That is the conversation I hope more women feel able to have with their partner, a professional or simply with themselves. It rarely starts with a plan. It starts with a question. If this is a conversation you would like to continue, connect with me on Linkedin or email me at helenthomas@melbournecapitalgroup.com. I’m always glad to hear how other women are approaching this.

Explore our Insights
Our team of global experts share their perspective on markets and news from the company.